

Friday, 27/03/2026, 06:00 (GMT +7)
 594
Geopolitical 'Undercurrents' and the Restructuring Race Reshaping the Global Shipping Map

Trade, not bombs, is the true fuel that builds today's superpowers. Ocean shipping has always acted as the "spearhead" for the vast majority of transnational business operations. Any disruption in the maritime domain creates a ripple effect that severely impacts the entire supply chain.
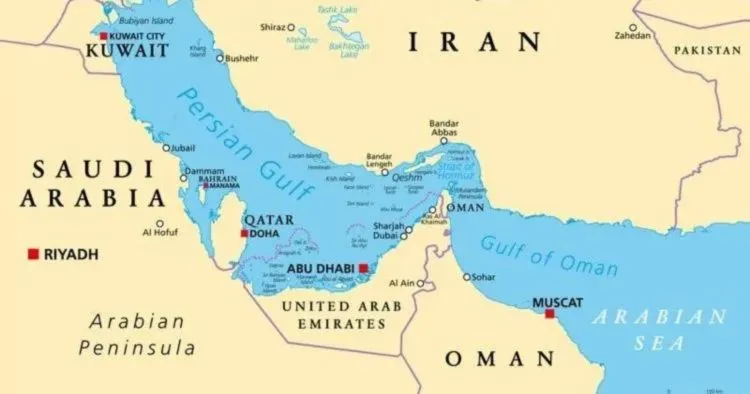
Amidst Iran's blockade of the Strait of Hormuz to most oil tanker traffic, a surprising truth is that crude oil is no longer the market's biggest threat. The real risk factor lies in the 10-year US Treasury bond - the very financial instrument that forced President Donald Trump to back down from his "Liberation Day" tariff policies this past April, as investor fears pushed yields past the 4.60% mark.
With current yields sitting at 4.40% and the conflict showing no signs of ending, some analysts forecast that the 10-year Treasury could spike to 4.50% and even 4.60%. These figures will once again severely test the market's resilience. Despite these variables, bunker fuel prices will undoubtedly dictate shipping plans, especially at a time when shippers are locking in annual contracts with ocean carriers.
The true impact of the war on the global container shipping industry has yet to be fully revealed, given that only about 2% to 3% of total global cargo volumes transit through the Middle East. However, when converted, this percentage equates to roughly 6 million containers - a massive volume, second only to the capacity of the world's largest shipping line, Mediterranean Shipping Co. (MSC), which commands 7.2 million TEUs.
Dual Crisis Locks Down Vital Maritime Routes
While tens of thousands of seafarers and hundreds of vessels remain trapped in the Persian Gulf, major shipping lines have also suspended scheduled services through the Red Sea and the Suez Canal since late 2023. This marks the first time in history that the Middle East's two busiest trade corridors have been closed simultaneously.
The root cause stems from Houthi rebel forces in Yemen persistently attacking commercial vessels. In 2024, ocean carriers recorded windfall profits amounting to tens of billions of dollars, driven by extended voyages as ships were rerouted around the Cape of Good Hope (Africa) to avoid the Red Sea.
Currently, Houthi forces are threatening to blockade the Bab-el-Mandeb Strait, located between the Red Sea and the Gulf of Aden. Although support from Iran shows signs of waning, these threats are enough to force shipping lines into another swift retreat, just as they were tentatively testing a return to the Red Sea prior to the outbreak of the war in Iran.
Reshaping the Trade Map and the Profitability Puzzle
Shifts in trade routing driven by tariff impacts are becoming highly visible across global markets. For the United States, an increasing volume of Asian imports is being diverted to Mexico and Canada, subsequently penetrating the US market via rail and cross-border trucking. This has siphoned off a portion of the volume from the Southern California import gateway, although resilient consumer purchasing power has still allowed the ports of Los Angeles and Long Beach to maintain positive results.
Meanwhile, China's aggressive export push in 2025 created a tidal wave of goods flooding into Europe, turning port congestion into a "new normal."
However, global economic instability, shifting trade flows, and a massive influx of newbuild tonnage entering the market pushed the profits of some of the largest shipping lines into the red in 2025. The industry's harsh cyclicality has returned in the post-pandemic era, once again raising the fundamental question: Is it possible to maintain stable profitability in the shipping industry?
The Wave of Consolidation and Strategic Pivots
Rather than waiting for an answer, the industry's "giants" are proactively executing new strategic moves:
● MSC ventures into the energy sector: Over the past week, MSC acquired a 50% stake in South Korea's Sinokor, thereby securing a fleet of 78 Very Large Crude Carriers (VLCCs). This move helps MSC diversify its risks away from the cyclical nature of the container segment, targeting greater stability in the energy market through a joint venture with a long-term strategic vision.
● Maersk dives deeper into the last mile: The world's second-largest ocean carrier is ramping up its forwarding logistics arm with Maersk Parcel, aiming to close the final gap from the warehouse to the consumer's hands. This single platform provides shippers with one bill of lading, one invoice, one tariff, and a seamless tracking experience.
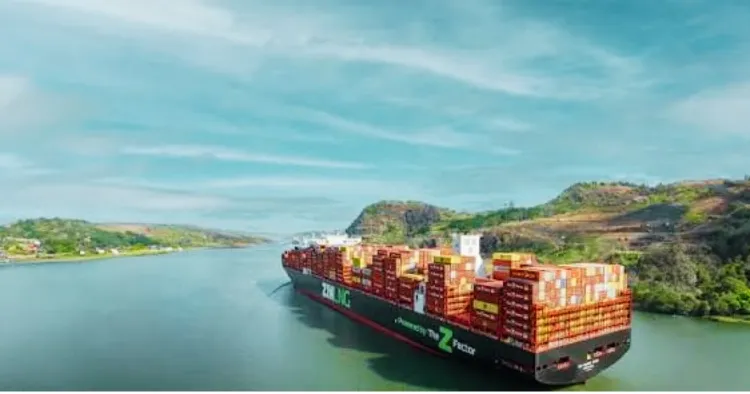
● Hapag-Lloyd acquires ZIM: In another notable Top 10 consolidation deal, ZIM (ranked 10th) agreed to be acquired by Hapag-Lloyd (ranked 5th) for $4.2 billion in February. This transaction bolsters Hapag-Lloyd's scale and reach, particularly on the Trans-Pacific trade lanes, where its market share is projected to grow from 7% to 12%.
The market is currently continuing to hypothesize scenarios of further consolidation among smaller container lines - entities that lack the capital depth to survive in such a highly volatile market.
See more:
- Despite Airspace Risks, Qatar Cargo Resumes Dedicated Freighter Flights from Doha
- COSCO Shipping in 2025: Container Volumes Rise 6% as Digitalization and Green Fleet Expansion Accelerate
- Dubai Aviation: Sustaining Supply Chains Amidst the Middle East Geopolitical Storm
- Maersk Relocates PANZ Service to Fenix Marine Terminal
- 2026 Dry Bulk Market: Will the Growth Momentum Continue?
- International Shipping and Logistics Market Update Week 12/2026 | Phaata
- Middle East Tensions: Maersk Imposes Global Fuel Surcharges
- Port Dispute: Panamanian President Rejects Hutchison's Accusations
- Hapag-Lloyd and India Establish a Strategic Maritime Cooperation Framework
- MSC Group Inks Deal to Acquire 50% Stake in Sinokor Maritime
- The Future of the ZIM Deal: Regulatory Hurdles for Hapag-Lloyd and Maersk's Contingency Plan
- Hormuz Shock: Over 204,000 TEUs at Risk of Being 'Trapped', Specter of Empty Container Shortages Returns to Asia
- COSCO schedules: Vietnam - North America in Mar 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Mar 2026
Source: Phaata.com (According to Freight Waves)
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more

 HOT PROMO
See more
4
 FCL
 39 Days
 Freight cost
Savino Del Bene
10
FCL
35 Days
Freight cost

OPL LOGISTICS
821
FCL
2 Days
Freight cost

CÔNG TY TNHH PIO LOGISTICS
1729
FCL
31 Days
Freight cost

CÔNG TY TRÁCH NHIỆM HỮU HẠN DT LOGISTICS (VN)
2783
FCL
30 Days
Freight cost

CÔNG TY TNHH PEGASHIP
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
3
16
Days Direct
- ₫58,218,600 / 20'GP

CHI NHÁNH THÀNH PHỒ HỒ CHÍ MINH - CÔNG TY TNHH HECNY SHIPPING VIỆT NAM
23
40
Days Direct
- ₫196,223,145 / 20'GP
- ₫229,301,895 / 40'GP
- ₫229,301,895 / 40'HQ
ALLIANCE INTERNATIONAL LOGISTICS CO., LTD
 Premium
240
 259
22
Days Direct
- ₫179,948,400 / 40'RQ
CÔNG TY CỔ PHẦN QUỐC TẾ ANVY
251
13
Days Direct
- ₫75,419,550 / 40'RQ

CÔNG TY TNHH VẬN CHUYỂN QUỐC TẾ RYLOGS
Sea freight
- LCL
See more
637
7
Days Direct
- ₫105,852 /cbm

Công ty Cổ phần vận tải xuyên đại dương OVC
3,226
4
Days Direct
- ₫26,463 /cbm

CÔNG TY TNHH IEC EXPRESS (VIỆT NAM)- CHI NHÁNH HÀ NỘI
4,288
5
Days Direct
- ₫26,463 /cbm

CHI NHÁNH TẠI THÀNH PHỐ HỒ CHÍ MINH - CÔNG TY CỔ PHẦN MG LOGISTICS
4,704
8
Days Direct
- Refund ₫2,362,500 /cbm

CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
4,916
4
Days Direct
- ₫26,463 /cbm

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI MỸ Á (ASL LOGISTICS)
 Air freight
- General cargo
See more
1,765
10
Days Transit
- 264,630 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
2,866
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
6,204
 5,772
8
Days Transit
- 224,936 ₫/kg

CÔNG TY TNHH SEA GLOBAL VIỆT NAM
3,161
1
Days Direct
- 502,797 ₫/kg

CÔNG TY TNHH VẬN TẢI QUỐC TẾ GIA PHÚ
 Rail freight
- FCL
See more
43
5
Days Direct
- ₫44,987,100 / 40'HQ
- ₫44,987,100 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
338
3
Days Direct
- ₫15,083,910 / 40'HQ
CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
11,301
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
10,526
5
Days Direct
- ₫7,145,010 / 20'GP
ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
8,532
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
45
1
Day
- ₫28,000,000 / 20'GP
- ₫28,000,000 / 40'GP

CÔNG TY TNHH THƯƠNG MẠI DỊCH VỤ VÀ KHO VẬN VIETTEL POST - TTC
77
4
Day
- ₫211,704 / 20'GP

CÔNG TY CỔ PHẦN KINH DOANH THƯƠNG MẠI VÀ DỊCH VỤ HỎA TỐC
43,358
1
Day
- ₫6,868,686 / 20'OT
- ₫6,868,686 / 40'OT
- ₫6,868,686 / 40'OT HQ
CÔNG TY TNHH LIÊN VẬN QUỐC TẾ SHINING OCEAN VIỆT NAM
101,112
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
171,152
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG


