


Wednesday, 11/11/2026, 10:00 (GMT +7)
 10
European road freight rates level off at record highs in Q3 2026
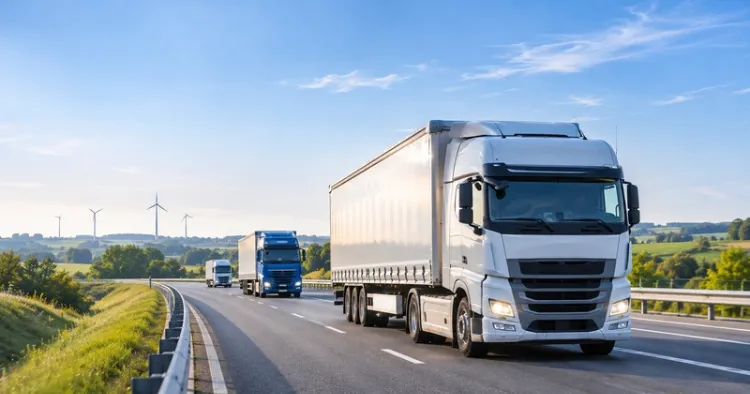
The Upply x Ti x IRU European road freight rates report on Q3 2026 found that both benchmarks leveled off at record levels after sharp increases in the first half of the year. The driver was cost rather than demand: average diesel price reached a record EUR 2.27 per liter on September 27 in the EU, while road trade volumes between major EU economies fell 4.5% quarter on quarter.
The report was published by the IRU (World Road Transport Organisation) on November 10, 2026.
Key indicators
- Contract rates rose to 148.9 index points, a modest 0.8-point increase quarter on quarter (QoQ) and 14.6 points higher year on year (YoY).
- Spot rates edged up 0.8 points QoQ to 147.6 index points, 12.9 points higher YoY.
- Diesel prices: The EU weighted average diesel price was EUR 2.05 per liter in Q3, 6% above Q2 and 32% above Q3 2025, peaking at EUR 2.27 per liter on September 27, above both the April record and the all-time high of June 2022.
- Operating costs: fuel accounted for almost all of the rise in operating costs. The French National Road Committee (CNR) long-haul truck index rose 13.2% YoY in September 2026, but only 1.3% excluding diesel.
- Volumes: road trade volumes in metric tons between major EU economies fell 4.5% QoQ and stand 4.2% below the same period of 2025, according to Eurostat. Spain-France (-5.4% QoQ) was the weakest corridor and Poland-Italy (+0.7%) the only one to grow.
- Tolls: IRU's EU toll index stood at 116.6 in Q3, 7% above a year earlier and 17% above early 2023.
- Heavy truck registrations: about 60,100 units were registered in the EU in Q3 2026. Growth over the trailing 12 months to September slowed to 7.0%, down from 8.4% in June, the first easing since the recovery began in early 2026.
- Germany: recorded the strongest domestic movements, with contract rates at 164.9 index points (up 21.6 points YoY) and spot rates at 148.3 index points (up 28.3 points YoY).
- Q4 outlook: rates are expected to stay high, with cost pass-through rather than volume growth continuing to do most of the work.
- European Road Freight Sentiment Index (Ti x Upply x IRU) fell by 4.7 index points to 23.6 in Q3 2026, easing back from last quarter's record high but remaining the second-highest reading on record, with 81.2% of respondents expecting rates to rise over the next three months.
Cost dominates, demand contributes little
Both benchmarks rose by only 0.8 points in Q3, a marked slowdown from the sharp increases of the first half of the year, and both ended the quarter at series highs. The flattening reflects a market in which cost pass-through has become the dominant mechanism and demand is contributing little.
The euro area Economic Sentiment Indicator (ESI) fell 0.5 points in September to 97.9, drifting back below its long-term average of 100. Road trade volumes between major EU economies fell 4.5% QoQ against a 1.7% seasonal decline over the same months of 2025, with the decline broad based across the main corridors.
Diesel is the source of pressure on rates
The EU's weighted average diesel price rose through the whole quarter to average EUR 2.05 per liter, reaching EUR 2.19 in September alone. It crossed EUR 2 per liter on July 22 as the Strait of Hormuz closed for a second time and peaked at EUR 2.27 per liter on September 27, 39% above the pre-war level of February 27.
Unlike the spring, the driver was not crude but diesel itself. The collapse of Middle Eastern and Russian diesel exports, refineries running at their limits on both sides of the Atlantic and record product tanker rates pushed Northwestern European diesel refining margins above USD 100 a barrel in early September.
Ti Head of Commercial Development Michael Clover said, "With the contract and spot indexes sitting at record levels, it's hard to look past diesel prices and the conflict in Iran, and to a lesser extent in Ukraine, as the primary drivers of the cost pressure we're seeing now. And it's very difficult to see these geopolitical events unwinding anytime soon. So we can expect diesel prices to remain elevated over the winter, and therefore, given that high rates are being sustained primarily by diesel prices, we would expect rates to remain elevated. Especially as demand picks up into the holiday season."
Divergence between domestic markets
The scale of the fuel effect is visible in the cost data: the CNR long-haul truck index rose 13.2% YoY in September 2026, but excluding diesel the increase was just 1.3%. National divergence widened accordingly.
- Germany: domestic contract rates reached 164.9 index points, up 21.6 points YoY, and domestic spot rates 148.3 index points, up 28.3 points YoY, helped by drought restrictions on Rhine navigation from July that shifted freight onto road and rail.
- Spain: domestic spot rates remained the highest of the four markets at 168.5 index points but grew the least, up 7.8 points YoY.
- France: domestic spot rates fell 3.6 points QoQ to 143.9 index points.
Policy: pulling in both directions
By mid-September, 16 EU countries still had fuel measures in place, most of them scaled back, and a further round expired on September 30 before record prices forced a partial reversal in early October.
Tolling added to the cost base rather than offsetting it, with IRU's EU toll index 7% above a year earlier, although the Netherlands has cut its new distance-based truck toll by 22.3% for the final four months of the year.
IRU Associate Director for Strategy and Market Intelligence Marie-Anne Cervoni said, "Record fuel costs, rising tolls and weaker demand are squeezing Europe's operators. Diesel prices exceeded their 2022 peak in September, and road freight volumes between major EU economies fell by 4.5% quarter on quarter. Fuel prices change every week, but freight rates are less volatile, putting operators' financial health at risk. The recovery in truck sales is slowing, and the number of operators is declining in several countries. Governments must replace stop-and-go relief with predictable support, otherwise Europe will lose transport capacity it cannot quickly rebuild."
Outlook
Diesel remains the single most important variable for Q4. The International Energy Agency (IEA) expects European delivered diesel prices to rise again as product tanker rates climb, heating oil stocks that were not replenished over the summer are rebuilt in competition with trucks, and the gasoil market stays tight well into 2027. IEA members agreed in October to accelerate the release of a further 100 million barrels with diesel prioritized, which could cap prices. Most national fuel measures run only to October 31 or December 31, so pump prices will depend as much on fiscal decisions as on the market.
Demand is unlikely to provide much of a lift. The slowdown is driven by real incomes rather than interest rates, with disposable income barely growing after inflation and households running down savings. Peak season should still help, with volumes likely to spike around Singles' Day, Black Friday and Cyber Monday. The European Central Bank (ECB) forecasts euro area growth of 0.9% in 2026 and 1.4% in 2027. Based on IRU's forecast, that translates into metric ton-kilometer growth of 0.5% in 2026 and 1.5% in 2027, conditional on sufficient transport capacity.
Capacity is the constraint to watch. Registration growth is easing and the pattern points to fleets deferring renewals rather than adding capacity, while operator numbers are falling in several markets and bankruptcies are still rising in Belgium. Trade policy has eased slightly: the 10% Section 122 surcharge lapsed on July 24 and the Section 301 tariffs that replaced it cap total duty on most EU goods at 10%, below the rate applied in the first half of the year.
The sentiment index eased back but did not change direction: respondents moved from expecting a substantial increase in rates to expecting a slight one. Combined, 81.2% still expect rates to rise over the next three months.
Upply Chief Executive Officer Thomas Larrieu said, "Q3 shows a market settling at record levels. After a sharp first half, contract and spot rates have stopped climbing as fast, but show no sign of easing, driven more by operating costs than by freight demand. Behind the European average, domestic markets are moving at different speeds, with German rates rising steeply while French spot rates softened over the quarter. As shippers and operators prepare their 2027 contract negotiations, understanding these differences across corridors and markets will be key to setting the right price levels."
See more:
- COSCO Shipping Energy Plans 24-Vessel VLCC Fleet Expansion
- Evergreen's EVER EON Transits Suez Canal, Marking Return After Nearly Three Years of Disruption
- International Shipping and Logistics Market Update Week 45/2026 | Phaata
- MSC Extends PRS and SCS Coverage to All Mediterranean and Black Sea Ports
- Hapag-Lloyd Imposes US$400/TEU PSS on Cargo from Asia and Oceania to Tema
- Kuehne+Nagel Port Operations Update: Vessel Waiting Times in Ningbo and Shanghai Exceed Two Days
- BIMCO Releases Contract Addendum Establishing Framework for Sharing Costs and Benefits of Fuel-Saving Retrofits
- Hapag-Lloyd Implements $500/TEU Peak Season Surcharge on Asia and Oceania to South Africa Trades
- Over 35,000 Containers Await Rail Transport at the Los Angeles–Long Beach Port Complex
- THE NORTHWEST SEAPORT ALLIANCE HIGHLIGHTS TRANSPACIFIC GATEWAY ADVANTAGES AND INFRASTRUCTURE INVESTMENTS AT NOVEMBER 4 EXECUTIVE ROUNDTABLE IN HO CHI MINH CITY
- COSCO schedules: Vietnam - North America in Nov 2026
- COSCO updates Vietnam-North Europe sailing schedules in Nov 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Nov 2026
Source: Phaata.com
► Find Better Freight Rates & Logistics Service Providers!
Reference source: The IRU (World Road Transport Organisation) - https://www.iru.org/news-resources/newsroom/european-road-freight-rates-steady-record-highs


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more

 HOT PROMO
See more
86
 FCL
 10 Days
 Freight cost

NP LOGISTICS CO.,LTD
11354
FCL
35 Days
Freight cost
CÔNG TY TNHH CARDINAL GLOBAL LOGISTICS (VIETNAM)
 Premium
1756
FCL
15 Days
Freight cost

Compass Logistics
Premium
5342
FCL
38 Days
Freight cost
CHI NHÁNH THÀNH PHỒ HỒ CHÍ MINH - CÔNG TY TNHH HECNY SHIPPING VIỆT NAM
6989
 Other

INTERLOG CORP - CÔNG TY CỔ PHẦN GIAO NHẬN TIẾP VẬN QUỐC TẾ
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
10
20
Days Direct
- ₫51,602,850 / 20'GP
- ₫60,864,900 / 40'GP
- ₫60,864,900 / 40'HQ
- ₫60,864,900 / 45'HQ
HAFA TRADING & LOGISTICS COMPANY LIMITED
11
25
Days Transit
- ₫63,140,718 / 20'GP
- ₫114,796,494 / 40'GP
- ₫114,796,494 / 40'HQ

CÔNG TY TNHH GRAND OCEAN LINE VIỆT NAM
27
40
Days Transit
- ₫61,791,105 / 20'GP
- ₫97,119,210 / 40'HQ
Compass Logistics
Premium
607
3
Days Direct
- ₫3,175,560 / 20'GP
- ₫7,145,010 / 40'GP
- ₫7,145,010 / 40'HQ
GIA LINH LOGISTICS SERVICES CO., LTD. (G LINK Logistics)
573
6
Days Transit
- ₫14,554,650 / 20'GP
- ₫29,109,300 / 40'HQ
CÔNG TY TNHH GIAO NHẬN TOÀN CẦU GS
Sea freight
- LCL
See more
677
12
Days Direct
- Refund ₫264,630 /cbm

CÔNG TY CỔ PHẦN SILVIET
1,028
 2,574
13
Days Direct
- ₫0 /cbm
CÔNG TY TNHH DỊCH VỤ VẬN TẢI BIỂN VESTAL
4,212
45
Days Transit
- Refund ₫131,570 /cbm
CÔNG TY TNHH LIÊN KẾT HOÀN HẢO (PERFECTLINK CO.,LTD)
5,925
7
Days Direct
- Refund ₫261,590 /cbm
CÔNG TY TNHH VẬN TẢI VÀ TIẾP VẬN TOÀN CẦU
 Air freight
- General cargo
See more
2,168
 10,770
1
Days Direct
- 46,310 ₫/kg

N.B.L INTERNATIONAL TRANSPORT CO., LTD
12,934
1
Days Direct
- 161,424 ₫/kg
CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI HỒNG SƠN
15,268
10
Days Transit
- 264,630 ₫/kg
Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
14,603
1
Days Direct
- 185,241 ₫/kg
CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
 Rail freight
- FCL
See more
11,657
5
Days Direct
- ₫44,987,100 / 40'HQ
- ₫44,987,100 / 45'HQ
CÔNG TY TNHH PHƯỚC TÁ
15,184
3
Days Direct
- ₫15,083,910 / 40'HQ
CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
24,770
7
Days Direct
- ₫48,956,550 / 20'GP
Công ty TNHH T&M Forwarding
23,224
5
Days Direct
- ₫7,145,010 / 20'GP
ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
11,864
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
565
6
Hour
- ₫10,500,000 / 40'GP
- ₫10,500,000 / 40'HQ
Công ty TNHH Giao nhận quốc tế HP LINK
623
 16,949
1
Day
- ₫28,000,000 / 20'GP
- ₫28,000,000 / 40'GP
CÔNG TY TNHH THƯƠNG MẠI DỊCH VỤ VÀ KHO VẬN VIETTEL POST - TTC
117,671
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
184,158
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG


