


Monday, 21/09/2026, 14:37 (GMT +7)
 10
Container Freight Rates on Asia–US Routes Near Pandemic-Era Peaks
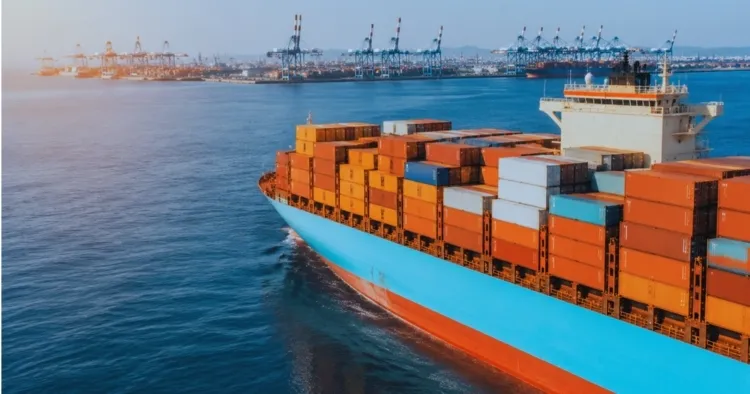
The upward momentum in container freight rates on the transpacific trade is expected to continue into early October as shipping demand builds ahead of China’s Golden Week holiday. At the same time, carrier capacity management, operational disruptions at Chinese ports and geopolitical uncertainty are simultaneously influencing market conditions.
Drewry and Xeneta both expect spot rates on the transpacific trade to continue rising in the short term. However, their views differ on the key drivers. Drewry emphasizes carrier-led capacity management, while Xeneta and Dynamar point to the combined impact of pre-Golden Week demand, geopolitical tensions and weather-related operational disruptions.
Carriers Adjust Capacity Ahead of Potential Market Reversal
Assessing capacity developments, Peter Sand, Chief Analyst at Xeneta, said:
“Carriers are seizing the opportunity while the market is hot, adding capacity into US East Coast ahead of what could be a turn in the market within the next two to three weeks. Offered capacity on the Far East to US East Coast trade is 6-7% higher in September than in August.”
While some carriers are increasing capacity on specific services, Drewry recorded nine blank sailings for next week, up from eight the previous week.
Drewry said: “Drewry expects rates to rise slightly next week [week beginning 21 September] amid impending pre-Golden Week demand and continued capacity management by carriers.”
In its spot rate report published on 17 September, Drewry said rates from Shanghai to Los Angeles increased 5% week on week to USD 7,712/FEU. Rates from Shanghai to New York rose 7% to USD 10,394/FEU.
The increases come as shipping demand typically strengthens ahead of Golden Week, China’s extended holiday period beginning on 1 October.
Spot Rates Move Closer to Pandemic-Era Peaks
In its weekly update, Xeneta said spot rates to the US West Coast and East Coast are currently 18% and 11% below, respectively, the highest levels recorded during the supply chain disruptions caused by Covid-19.
Xeneta noted: “Just 18% and 11% [respectively] short of the all-time high set during the Covid-19 disruption.”
With marine fuel prices increasing fuel costs and related surcharges, Xeneta warned:
“Surpassing the pandemic peak cannot be ruled out, which would be an extraordinary market development.”
According to Peter Sand, the fact that the market is even considering such a possibility highlights the sensitivity of major ocean container shipping routes to geopolitical developments: “the fact we are even discussing the possibility demonstrates how sensitive critical ocean container shipping trades are to geopolitical forces and how a regional conflict in the Middle East can have major implications at a global level. ”
Sand expects the market could see another rate increase in early October:
“We should expect one more freight rate push at the start of October as shippers rush cargo out of Asia ahead of the Golden Week shutdown, before rates start to soften, or at least the pace of growth will slow.”
Disruptions at Chinese Ports Continue to Add Pressure
In addition to demand and capacity, operational disruptions at Chinese ports are also affecting the market.
According to Darron Wadey, an analyst at Dynamar, a series of storms has disrupted operations at Chinese ports.
Destine Ozuygur, an analyst at Xeneta, said that by the end of August, approximately 1.1 million TEU of cargo was waiting at anchorage areas around three major Chinese gateways. Average delays are expected to exceed four days this month.
In the previous month, around 3.25 million TEU experienced schedule delays of more than 10 days, while only around 6% of capacity on the Asia–Europe trade arrived at ports on schedule.
Ozuygur said: “Each week of disruption often requires 1-3 weeks of recovery depending on port size and carrier strategy.”
These disruptions affect not only vessel schedules directly, but can also extend vessel and container turnaround times, thereby influencing capacity allocation across different trades.
Panama Restrictions Add Further Pressure on Cargo Flows
In addition to weather-related disruptions in China, restrictions related to draft limitations at the Panama Canal could also affect cargo flows.
Darron Wadey of Dynamar said: “The Panama Canal restrictions will also have an influence on the flow of goods .”
He said shifting part of the cargo flow to the US West Coast is not a solution that can be sustained over the long term:
“Redirecting trade flows to the US West Coast can only be a temporary solution otherwise congestion could appear in those gateways.”
This highlights that the ability to adjust routings depends not only on freight rates but also on the handling capacity available at alternative ports.
Prolonged Disruptions Could Increase Cargo Storage Costs
Another consequence of congestion is that cargo may remain on board vessels longer than expected, resulting in additional costs and longer transit times.
Wadey noted: “As we know, storage costs money and ships are perhaps the most expensive warehouses around.”
He added: “This would already result in elevated rates were everything else to remain equal.”
In addition to operational factors, the market is also being influenced by changes in US trade policy. Shippers have been bringing forward shipment schedules to mitigate the impact of trade measures expected to take effect or expire in the coming period.
According to Wadey, freight rates could decline after Golden Week, but the downward movement may only be temporary:
“A month after Golden Week ends, the 12-month truce on Chinese-built ships being charged to call US ports, and vice versa, comes to an end.”
Container Shipping Market Faces Multiple Variables
From developments in the Middle East and Europe to Africa, the container shipping market is currently being affected by multiple factors at the same time, making short-term freight rate forecasting increasingly difficult.
Wadey said: “To borrow [a phrase] from popular culture, we really are seeing everything... everywhere... all at once. That makes any form of prediction or planning nigh-on impossible unless someone, somewhere, takes a lead.”
With pre-Golden Week demand likely to continue supporting freight rates in the short term, while carriers adjust capacity and operational disruptions remain only partially resolved, the Asia–US trade is entering a period of heightened volatility. Freight rate developments in early October will depend on how long demand remains strong, the effectiveness of capacity management and the pace of recovery from port disruptions.
See more:
- Maritime Tensions: Iran Attacks Vessel in Hormuz as Italy Prepares Independent Red Sea Escort Plan
- SITC – CONNECTING CAMBODIA WITH VIETNAM AND THE WORLD
- Hapag-Lloyd CEO: Container Shipping Demand Remains Resilient Amid Geopolitical Volatility
- US Container Imports Reach 2.6 Million TEU, Third-Highest Volume on Record
- Prolonged Gulf Crisis Raises Biofouling Risks for Idled Vessels
- COSCO Shipping Heavy Industry Begins A-Share Listing Process in Shanghai
- International Shipping and Logistics Market Update Week 37/2026 | Phaata
- US-Iran Conflict Puts Growing Pressure on Maritime Operations in the Strait of Hormuz
- 18 Maritime Nations Warn of a “Structural Shift” in Global Trade
- Rotterdam World Gateway Completes €500 Million Financing for Expansion Project
- Maersk Updates PSS for Mediterranean–North America Trade
- Hapag-Lloyd and FIMI Given 30 More Days to Restructure ZIM Deal
- International Shipping and Logistics Market Update Week 36/2026 | Phaata
- COSCO schedules: Vietnam - North America in Sep 2026
- SITC updates Vietnam-Intra Asia sailing schedules in Sep 2026
Source: Phaata.com (According to Seatrade Maritime)
► Find Better Freight Rates & Logistics Service Providers!


Featured News
- Hapag-Lloyd applies Peak Season Surcharge from East Asia to USA and Canada
- The world\'s largest container ships MSC Irina and MSC Loreto floated
- MSC (Mediterranean Shipping Company) - The world\'s leading container shipping lines
- Information you need to know about Maersk Line
- Top 10 export and import goods between Vietnam - Philippines in the first 5 months of 2020

 Market News
See more





 HOT PROMO
See more
1118
 FCL
 45 Days
 Freight cost

Compass Logistics
 Premium
1915
FCL
40 Days
Freight cost

CÔNG TY TNHH PEGASHIP
2696
FCL
30 Days
Freight cost

CÔNG TY TNHH INTERNATIONAL LOGISTICS GLORY (VIỆT NAM)
4253
FCL
3 Days
Freight cost

Công ty TNHH Giao nhận vận chuyển Quốc tế Trường Hải - THILOGI
Premium
4232
FCL
10 Days
Freight cost

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ GREEN DRAGON VIỆT NAM
Why do thousands of businesses trust Phaata?
USERS/MONTH
LOGISTICS COMPANIES
REQUEST FOR QUOTEŚ
QUOTATIONS
VIETNAM LOGISTICS COMMUNITY
5 Steps to Get the Best Quote
Find a price quickly/Send a RFQ
Compare multiple options
Contact for Further Consultation
Negotiating prices/services
Management & rating
 Freight rates
Sea freight
- FCL
See more
17
25
Days Transit
- ₫30,432,450 / 20'GP
- ₫38,371,350 / 40'GP
- ₫38,371,350 / 40'HQ
- ₫38,371,350 / 45'HQ

T.H.I GROUP VIỆT NAM
35
8
Days Direct
- ₫34,087,300 / 40'HQ

CÔNG TY TNHH VẬN TẢI VÀ TIẾP VẬN TOÀN CẦU
44
5
Days Direct
- ₫44,540,000 / 40'HQ
CÔNG TY TNHH INTERNATIONAL LOGISTICS GLORY (VIỆT NAM)
43
 79
6
Days Direct
- ₫3,175,560 / 20'GP
- ₫5,821,860 / 40'GP
ORIENTAL LOGISTICS VIETNAM CO., LTD
Sea freight
- LCL
See more
1,826
4
Days Direct
- ₫26,463 /cbm

CÔNG TY TNHH IEC EXPRESS (VIỆT NAM)- CHI NHÁNH HÀ NỘI
2,878
5
Days Direct
- ₫26,463 /cbm

CHI NHÁNH TẠI THÀNH PHỐ HỒ CHÍ MINH - CÔNG TY CỔ PHẦN MG LOGISTICS
3,533
8
Days Direct
- Refund ₫2,362,500 /cbm

CÔNG TY CỔ PHẦN TIẾP VẬN INTERCARGO
4,103
4
Days Direct
- ₫26,463 /cbm

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI MỸ Á (ASL LOGISTICS)
4,219

 Air freight
- General cargo
See more
921
10
Days Transit
- 264,630 ₫/kg

Phoenix Logistics Vietnam - chi nhánh TP. Hồ Chí Minh (Phoenix International Forwarding Vietnam )
1,623
1
Days Direct
- 185,241 ₫/kg

CÔNG TY TNHH THƯƠNG MẠI VÀ DỊCH VỤ FASTRANS
5,143
 4,830
8
Days Transit
- 224,936 ₫/kg

CÔNG TY TNHH SEA GLOBAL VIỆT NAM
2,742
1
Days Direct
- 502,797 ₫/kg

CÔNG TY TNHH VẬN TẢI QUỐC TẾ GIA PHÚ
 Rail freight
- FCL
See more
684
5
Days Direct
- ₫26,463,000 / 40'HQ
- ₫26,463,000 / 45'HQ

CÔNG TY TNHH PHƯỚC TÁ
1,000
3
Days Direct
- ₫6,324,657 / 40'HQ

CÔNG TY CỔ PHẦN VẬN TẢI VÀ THƯƠNG MẠI ĐƯỜNG SẮT
10,345
7
Days Direct
- ₫48,956,550 / 20'GP

Công ty TNHH T&M Forwarding
9,722
5
Days Direct
- ₫7,145,010 / 20'GP

ASIAN EXPRESS LINE VIETNAM ( AEL VIET NAM )
8,186
10
Days Direct
- ₫9,262,050 / 20'GP

CÔNG TY CỔ PHẦN LOGISTICS QUỐC TẾ V&T
 Road freight
- FCL
See more
42,529
1
Day
- ₫6,868,686 / 20'OT
- ₫6,868,686 / 40'OT
- ₫6,868,686 / 40'OT HQ

CÔNG TY TNHH LIÊN VẬN QUỐC TẾ SHINING OCEAN VIỆT NAM
99,681
2
Day
- ₫6,500,000 / 40'RF
- ₫6,500,000 / 40'RQ
- ₫6,500,000 / 45'RQ

CÔNG TY CP PROSHIP
Premium
169,976
1
Day
- ₫18,997,200 / 20'GP
- ₫18,997,200 / 40'GP

CÔNG TY CỔ PHẦN GIAO NHẬN VẬN TẢI CON ONG
262,313
3
Day
- ₫32,000,000 / 20'GP
- ₫64,000,000 / 40'GP
- ₫64,000,000 / 40'HQ
- ₫64,000,000 / 45'HQ

Công ty Cổ phần phát triển thương mại Thuận Đạt Việt Nam
283,068


